The global race to secure critical minerals is accelerating. Demand for lithium, cobalt, copper and rare earths is projected to increase dramatically – in some cases by four times or more by 2040. This offers real development potential for producing countries, but also strategic geopolitical leverage, as these minerals are essential for clean energy, digitalisation, and security agendas, including militarisation.
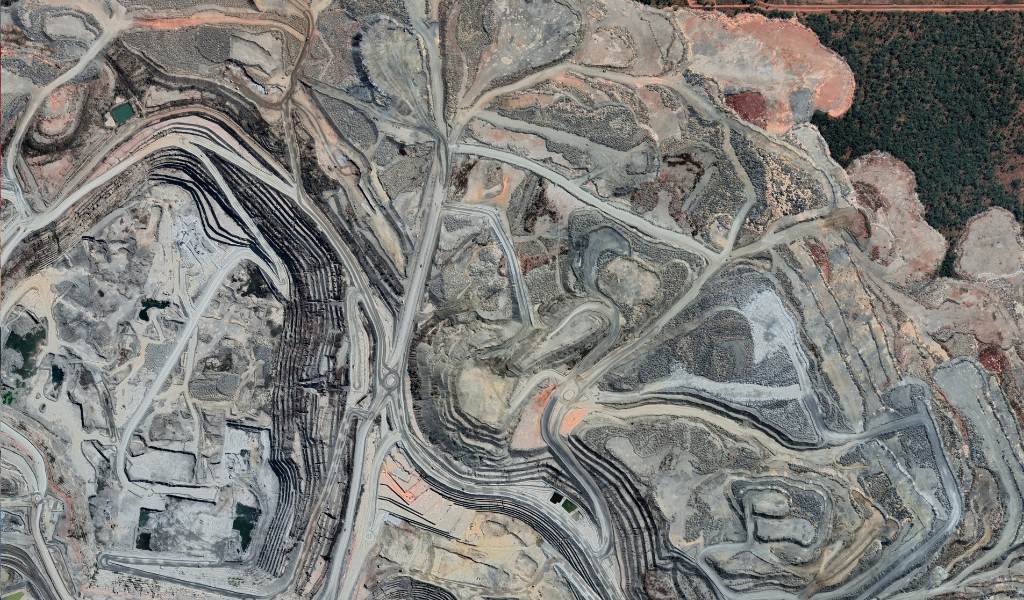
As in previous commodity booms, resource-rich but economically challenged countries are throwing themselves into the game – some with decades of extraction behind them, like Indonesia, DRC, Chile and Brazil – some new entrants, such as Zimbabwe, Namibia, Zambia and Uzbekistan, expanding fast. Against this backdrop, expectations are growing that this time minerals will deliver development. ‘This time, we will not export rocks’ is sustained as a flag. Zimbabwe’s Minister of Mines put it clearly: “no lithium bearing ores, or unbeneficiated lithium whatsoever, shall be exported.”
But this promise is one we have heard before. Price volatility, Dutch disease, enclave dynamics, weak linkages, and the corrosive effects of resource rents on institutions have repeatedly got in the way – and they are already reasserting themselves in the current boom, from the 70 percent lithium price collapse between 2022 and 2024 to persistent governance concerns in the DRC
The key question is whether this minerals boom can deliver for countries in a context which has changed in important ways.
Three challenges that change the stakes
Three fundamental challenges have changed the conditions for development from minerals.
First, mineral extraction is unfolding in the midst of a deep environmental crisis. Mining is highly resource-intensive, and is happening in regions already experiencing severe pressures on water, land and ecosystems. In Chile’s Atacama Desert, lithium extraction is consuming a growing share of local water supplies in regions facing acute drought. In Indonesia, the rapid expansion of nickel processing has brought deforestation, coastal degradation, and serious air and water pollution to some of the world’s most biodiverse landscapes.
Second, resistance to mining has become widespread and global. Conflicts around extraction are no longer isolated or localised phenomena, nor are they simply a symptom of weak institutions, as is sometimes implied. They reflect deeper questions of rights, distribution and participation, and as our recent research has shown, occur across regions and income levels, wherever mineral deposits are found.
Third, geopolitical tensions over access to minerals have intensified sharply. Access to key critical minerals is increasingly framed as a matter of national security rather than market efficiency. Major economies are coordinating strategies to secure supply, often through alliances and club arrangements. While this may create new leverage for some producing countries, it also reshapes the rules of the game, and not necessarily in ways that favour development.
Taken together, these challenges do not replace the classic problems of resource-based development, they amplify them. An important question is whether producing countries are better positioned today to navigate them.
New opportunities and reasons for cautious optimism
There are some reasons for cautious optimism.
Years of investment in industrial policy, education and innovation systems have built scientific, technological and productive capacities in many resource-rich low- and middle-income countries that simply did not exist in previous booms. At the same time, new technological opportunities- particularly in digital and modular domains – may lower entry barriers in certain segments of mining value chains.
There is also stronger determination to move beyond raw extraction – at least in ambition, and in some cases in policy too. Governments are experimenting with different policy approaches to capture more value: export restrictions, and new forms of state participation and local content requirements. Indonesia’s ore export ban is the most cited example, driving large-scale investment in domestic nickel processing and repositioning the country from raw ore exporter to a major player in refined nickel supply.
Finally, the global context has changed in ways that make environmental and social problems harder to ignore. Greater recognition of indigenous rights, gender inequalities and the broader impacts of extraction, alongside a more organised and globally connected civil society, means these concerns now carry real weight. Consumers in key markets are increasingly aware of where and how minerals are produced, and the pressure to reduce negative impacts grows.
These elements suggest that new pathways may be possible. But they are far from guaranteed.
New possibilities, old fragmentation
Traditional responses to resource dependency are well known: strengthen institutions, promote linkages, invest in industrial policy, build local content. These remain necessary. But the new challenges demand something different in kind, not just in degree.
Fortunately, the same context that raises the stakes has also brought new enablers. Many resource-rich countries today have stronger institutions, greater technical capabilities, and more policy experience than in previous booms. And we have learned something important: conditions long treated as structurally fixed – market concentration, processing dominance, technological lock-in – can be reshaped through deliberate strategy.
China has recently shown this to the world, systematically and at scale. Rich countries did it before them – though this was largely forgotten with the dominance of orthodox economic thinking that presented ‘market’ conditions as natural rather than constructed. The ceiling is higher than it is often assumed.
However, isolation will not allow most resource-rich countries to reshape those conditions. Most are designing policies on their own, often without awareness of what others have tried, learned, or failed at. Advanced economies do not operate this way – they build coalitions, coordinate strategies, and defend shared interests. A striking example is TRIPs – a coordinated effort by rich countries to enforce strong intellectual property rules on economies that neither designed nor needed them (see Stiglitz). Resource-rich low- and middle-income countries, for the most part, have not coordinated in this way, and the costs of that fragmentation are rising.
At the same time, knowledge and analytical capacity remain heavily concentrated in richer economies, and the experiences of resource-rich countries in the South are not systematically documented or shared. The result is a striking replication of effort and a persistent inability to build the collective positions that this moment demands.
Resource-rich countries need to act together
Turning this mineral boom into a driver of development will therefore require more than favourable markets or better technologies. It will require coordination, learning, and new forms of governance that take these changing conditions seriously. The current geopolitical turbulence, for all its dangers, is also creating a window: demand is high, the old rules are being rewritten, and the leverage of resource-rich nations, if exercised collectively, is greater than it has been in decades.
The conditions that have historically made development from minerals so difficult are not as fixed as they appear. But reshaping them requires something that has so far been in short supply: collective strategy, shared learning, and the recognition that no country can do this alone. What this moment calls for is political will for coordination among resource-rich countries – on policy, on knowledge, on negotiating positions – and a serious investment in cross-learning across resource-rich economies in the South. Not as an act of solidarity alone, but as a strategic necessity.
The question is whether countries can act together to turn this mineral boom into a driver of development before the window closes.
To learn more about this issue, watch the recording of a recent event with Anabel Marín, IDS Research Fellow, Institute of Development Studies; Erika Kraemer-Mbula, University of Johannesburg and Ann Kingiri, African Centre for Technology Studies, Kenya.
Watch ‘Critical minerals and development: old wine in new bottles?’